Investment Advisory

Investment Advisory
The RBI has introduced a temporary package aimed at attracting foreign currency inflows from Non-Resident Indians (NRIs). The measures make eligible Foreign Currency Non-Resident (Bank) [FCNR(B)] deposits significantly more attractive by enabling banks to offer higher deposit rates while also providing additional flexibility for structured financing solutions.
The special window is available for fresh FCNR(B) deposits with maturities of 3–5 years mobilised up to 30 September 2026.
The RBI has introduced 3 key measures for eligible FCNR(B) deposits:
Let’s assume: You place USD 10 million in an FCNR deposit at 6.5. Against this, you obtain financing (via SBLC-backed borrowing) at ~5.5% & you deploy the borrowed funds into similar FCNR deposits.
So, on your own USD 10M → 6.5% = USD 650,000
| Particulars | Scenario 1 | Scenario 2 | Scenario 3 |
| FCNR(B) Deposit Yield | 6.5% | 6.5% | 6.5% |
| Cost of Borrowing | 6.0% | 5.5% | 5.0% |
| Spread | 0.5% | 1.0% | 1.5% |
| Leverage | 6× | 7× | 8x |
| Additional Return from Leverage (Spread × Leverage) | 3% | 7% | 12% |
| Return on Equity | ~9.5% | ~13.5% | ~18.5% |
* For Illustrative purposes only. Actual ROE will depend on financing costs, leverage achieved, fees, etc.
Following the RBI announcement, banks have revised FCNR(B) deposit rates upward. Indicative USD FCNR(B) rates for the 3–5 year tenor are presently as follows:
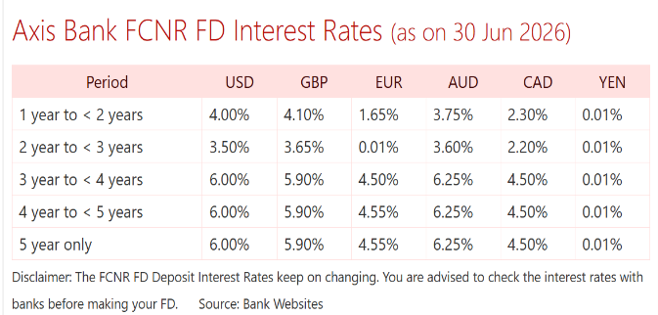
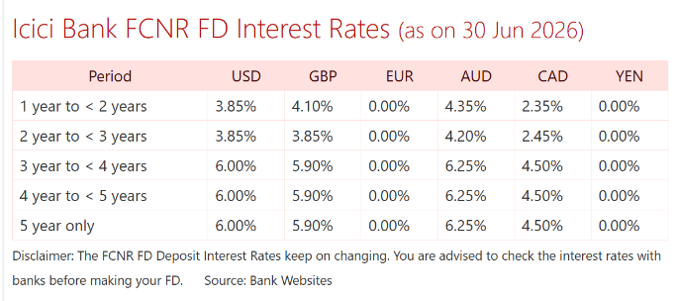
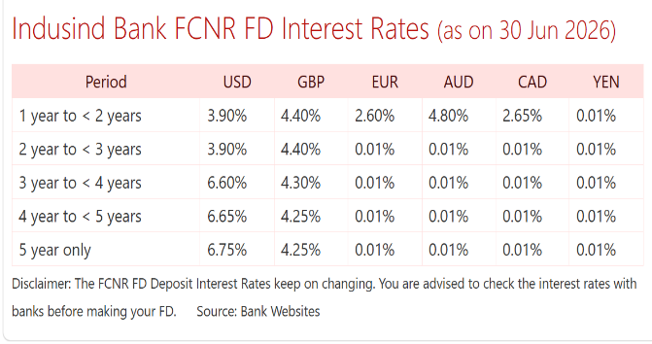
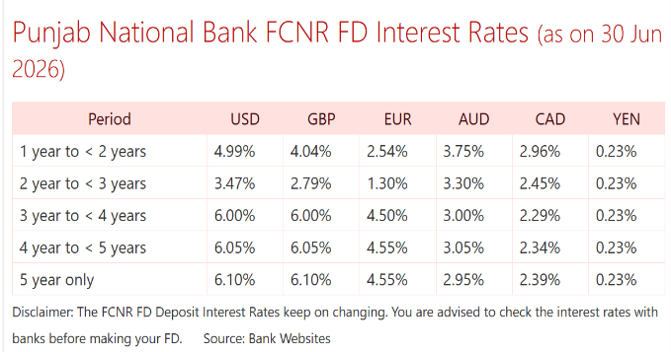
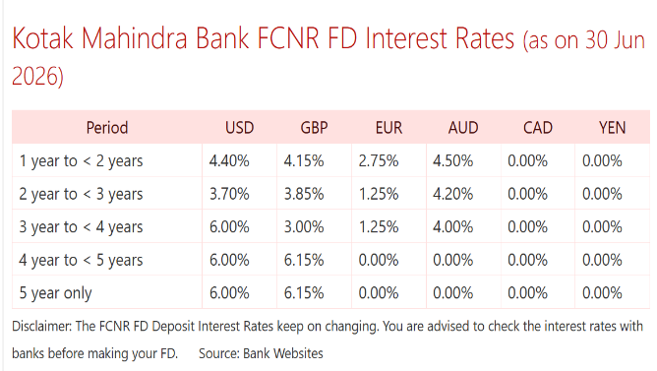
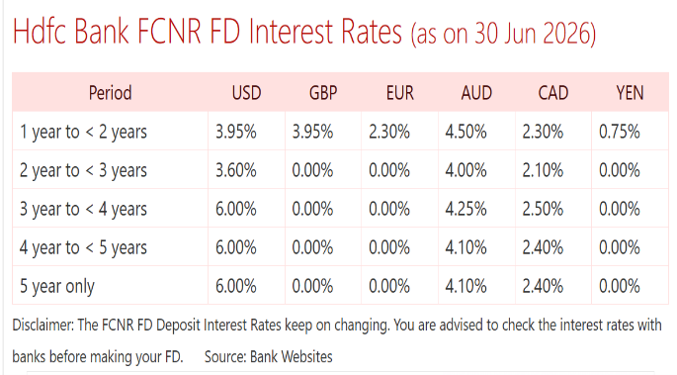
*Rates are as available on the respective banks’ websites. A value of ‘0%’ indicates that the bank has not published an FCNR(B) rate for that particular currency and/or tenor, and does not imply that the applicable interest rate is zero.
The current FCNR(B) window represents one of the most attractive foreign currency fixed-income opportunities available to NRIs in recent years. While elevated deposit rates are the primary attraction, the accompanying regulatory flexibility around collateralisation may also create opportunities, enabling investors to use prudent leverage, potentially resulting in double-digit USD returns subject to financing terms, costs, leverage, etc.
Given that the special RBI window is presently available only for eligible deposits mobilised up to 30 September 2026, investors may consider evaluating this opportunity in line with their liquidity requirements, currency preferences and overall investment objectives.
Every decision begins with a belief. We invest because we believe in an opportunity. We build businesses because we believe something can be done better. We prepare the next generation because we believe a legacy can evolve and endure. Those beliefs influence what we do. Our actions then change the circumstances in which we and […]
For a child who cannot hear, the challenge can extend far beyond hearing itself. It can affect how a child communicates, learns, participates in school and connects with the people around them. When support comes late, these challenges can shape a child’s opportunities well into adulthood. But early identification, the right support and an involved […]
The RBI’s 25 bps hike to 5.50% and its move from “neutral” to “calibrated tightening” came as a supply shock from West Asia pushed major central banks in the same direction. Within about a week in September, the ECB, the Fed and the Bank of Japan all raised rates while the Bank of England held […]
signup for updates