Investment Advisory

Investment Advisory
Financial markets regularly face crises – financial scandals, wars, inflation shocks, banking failures, pandemic, geopolitical stress, etc.
Each time markets fall sharply, investors ask the same question: “Is this the time to exit?”
History suggests the opposite.
Across decades of market data, crises have typically created temporary volatility but long-term opportunity.
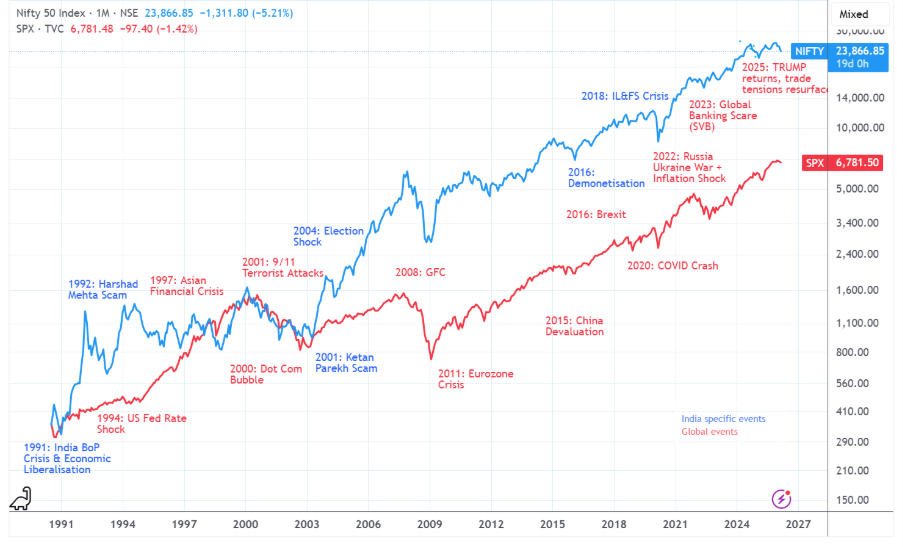
Over the past century, the S&P 500 has delivered roughly 9–10% annualised returns, navigating events such as the Great Depression, World Wars, oil shocks, the dot-com collapse, the Global Financial Crisis and the COVID-19 pandemic.
A similar pattern exists in India.
Since the mid-1990s, the Nifty 50 has compounded at approximately 13–14% annually, despite disruptions including the Asian Financial Crisis, the Global Financial Crisis, demonetisation, the IL&FS credit crisis and the COVID shock.
In other words, volatility has been frequent, but long-term compounding has remained intact.
Market declines during crises can be severe.
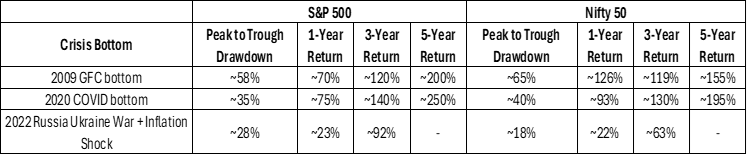
During the Global Financial Crisis, Indian equities fell nearly ~65% & S&P 500 58% from peak to trough.
Similarly, the COVID crash of 2020 saw the S&P 500 and Nifty 50 decline roughly 35% & 40% respectively within weeks, one of the fastest corrections in modern history.
Yet the recovery was equally dramatic.
Historical data suggests that market crashes in India have typically lasted around 8 months, while recoveries to previous highs often occurred within 16 months on average.
One of the biggest risks for investors during crises is attempting to exit markets and re-enter later.
Research shows that many of the market’s best days occur shortly after the worst declines.
Missing even a handful of these days can dramatically reduce long-term returns.
For example: According to J.P. Morgan, U.S. equities have delivered roughly ~10% annual returns over the long term, but missing just the 10 best trading days can cut those returns nearly in half compared to staying invested throughout.
This makes market timing during periods of volatility extremely difficult.
Some of the strongest market rallies in history have begun during periods of peak pessimism.
After the 2009 bottom during the Global Financial Crisis, global equities entered one of the longest bull markets in history.
Similarly, investors who deployed capital during the COVID-19 market panic in March 2020 saw significant gains in the years that followed. From the pandemic lows, equity markets delivered roughly ~172% returns in the US and nearly ~200% in India over the subsequent 5 years.
These episodes highlight a recurring pattern: the moments that feel most uncomfortable often create the most attractive long-term opportunities.
Financial markets are forward-looking.
Prices reflect expectations about future earnings, policy responses and economic recovery.
As a result, markets often begin rising while economic news still appears negative.
This is why many recoveries start when investor sentiment is still cautious.
Crises will continue to occur but history suggests that short-term volatility has rarely prevented long-term wealth creation.
While the current global environment presents its own set of unique uncertainties and that history may or may not repeat itself exactly, at Entrust we believe that disciplined investing that is anchored in diversified asset allocation, avoiding emotion driven decisions, a strong focus on long-term fundamentals and staying invested through market cycles, can help investors navigate these uncertainties while staying aligned with long-term wealth creation.
For patient investors, periods of crisis have often been the starting point of the next phase of wealth creation.
For a child who cannot hear, the challenge can extend far beyond hearing itself. It can affect how a child communicates, learns, participates in school and connects with the people around them. When support comes late, these challenges can shape a child’s opportunities well into adulthood. But early identification, the right support and an involved […]
The RBI’s 25 bps hike to 5.50% and its move from “neutral” to “calibrated tightening” came as a supply shock from West Asia pushed major central banks in the same direction. Within about a week in September, the ECB, the Fed and the Bank of Japan all raised rates while the Bank of England held […]
Markets are not driven by growth alone. They are not driven by inflation alone. It is the interaction between the two that shapes the investment environment. A useful way to think about global markets is through 2 simple questions: Is economic growth rising or falling? Is inflation rising or falling? Put these two forces together, […]
signup for updates